Summary
- The financial industry is rife with exaggerated performance claims, often driven by intense competition and marketing hype around ‘multibagger’ returns.
- In all my modeling I emphasize transparent, live-tested models and caution against relying on backtested or extrapolated returns that do not involve live markets.
- This article revisits published returns, comparative performance claims, and helps add clarity to how we should more accurately view market returns.
- Investors should maintain realistic expectations, focus on balancing risk-returns, avoid herding behaviors, and remain skeptical of marketing-driven performance narratives.
- Always feel free to reach out to me with your concerns and questions as I am glad to help.
Dissecting Financial Hype And Managing 5,100% Expectations
The financial investing world is full of hype and promises that set some enormously high expectations that are rarely achievable. In this article I set out to make some additional clarifications and in a rare, uncomfortable step I will make some critiques of other services’ performance marketing.
As a certified fraud examiner and anti-money laundering specialist it is easy for me to be over-analytical and critical of performance representations that I see all across the financial industry. Competition is intense and drives some institutions to manipulate or exaggerate outcomes. Performance charts are often stretched, chart axis may not start at zero, returns are extrapolated into the future, and performance data are favorably backtested for years to show enormous current returns.
Summary
This article addresses some frequent questions I receive about other service returns, clarifies and contrasts different portfolio performance results, and lastly attempts to show what realistic returns look like throughout history.
In a rare reversal of form, I will take on the role of critic to highlight concerns, pick at portfolio marketing, and hopefully provide a few insights that will give you some perspective in evaluating stock market claims in the future.
Where can I find your Multibaggers?
Some services and institutions lean heavily into the marketing of Multibaggers, stocks that have gone up by 100’s of percentages. 2x for 200% returns and 10-baggers for 1,000% returns. Their headlines scream “Get the next 10x Multibagger” and set expectations of 1,000% returns in their selections. I have had members ask me, why don’t you have any Multibaggers? or Where or your Multibaggers? Which one is your next Multibagger?
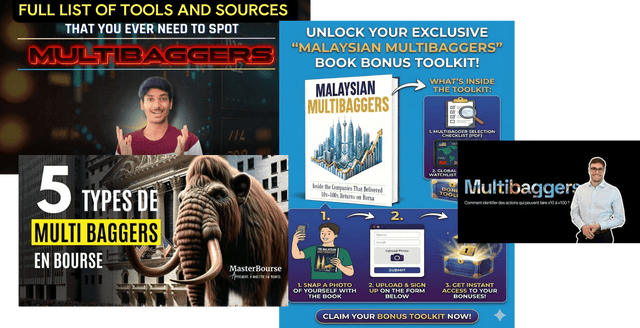
Headlines look like this, with promises on ways to find the next great stock with massive 10x to 100x returns. Obviously the first and biggest problem with this hype is time. None of these promises are anchored in a promise of any certain deadline. As such, every one of these services is always correct on their selections eventually reaching 10x or 100x as promised, simply because you just haven’t waited long enough. Give it more time and they will be 100% right, unless the stock delists or gets acquired. Even then, they may claim they were still 100% correct, but the stocks were just so good they got acquired or went private beyond the realm of measurement.
This is an area that I try to avoid and I address in my Getting Started Articles. Sometimes the craziness and the questions about multibaggers gets to be too much and so I put together a live updating list on the Dashboard Spreadsheet. Currently this list contains 239 stocks over 200% from the two weekly breakout models from 2019 through today. I don’t promote it, I don’t advertise it — but yes, I too have a list to show that even my models can deliver Multibaggers. If I wanted to fill it further, I could draw even more selections from across multiple portfolios. I don’t think this list helps you though. In my opinion, about all the list is good for is creating FOMO.
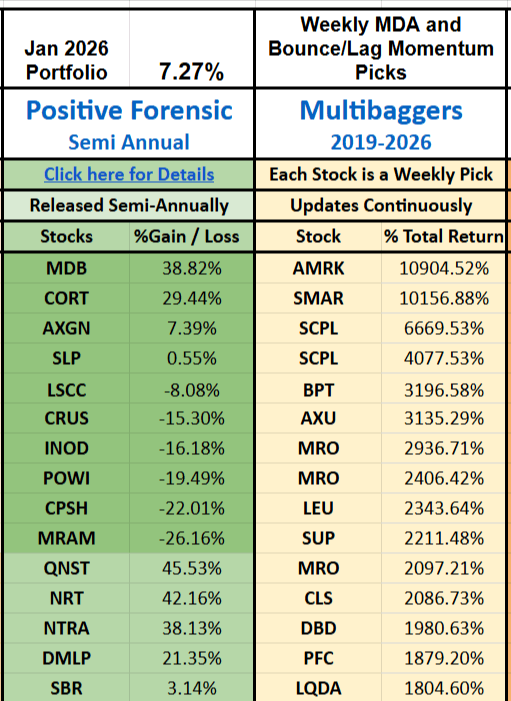
What no Multibagger list tells you is how CRAZY the ride was from 1% gains to 10,000% and how unlikely you would have been to even hold onto the wild rides from many of the winners — not to mention holding on to all the losers.
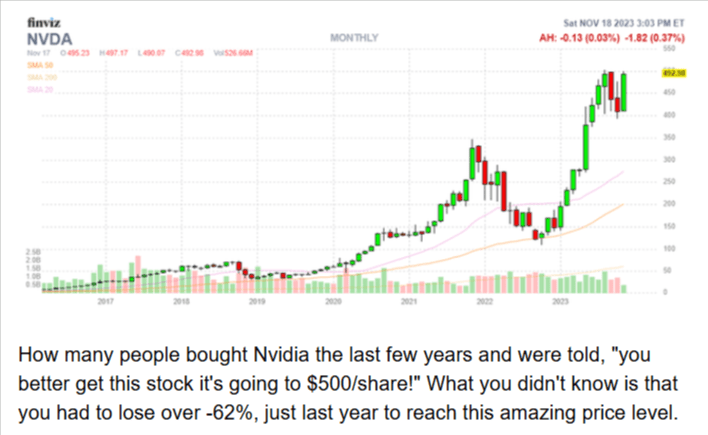
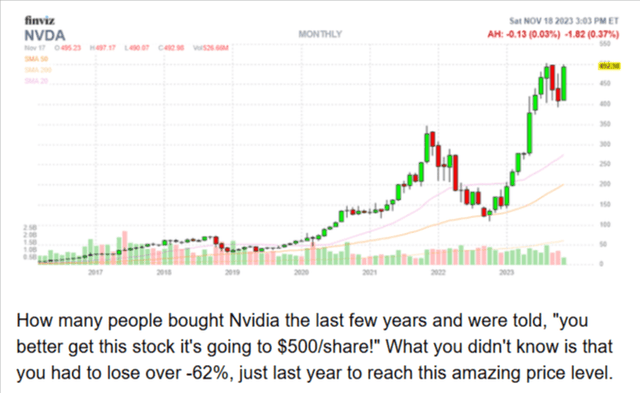
One of many articles I have discussed the Multibagger FOMO subject is on the topic of NVIDIA. So many analysts and services promote their claims of many 1,000% returns in this mega tech superstar. What they don’t tell you is whether they actually held through -62% losses as recently as 2022 and other very large declines in the stock’s history. I personally do not know anyone who holds -60% losses just because someone said the stock will eventually triple or quadruple one day.
This is an obvious form of hype that is very compelling like the Roaring Kitty crowd that created massive FOMO in social media picks to make enormously high risk short squeeze ventures seemingly attractive. You can make a lot of money in the big hype, but you can lose everything doing this as well. There are many reasons I try to avoid this approach in my service to you. No cat shirts and bandanas for me.https://seekingalpha.com/embed/31784
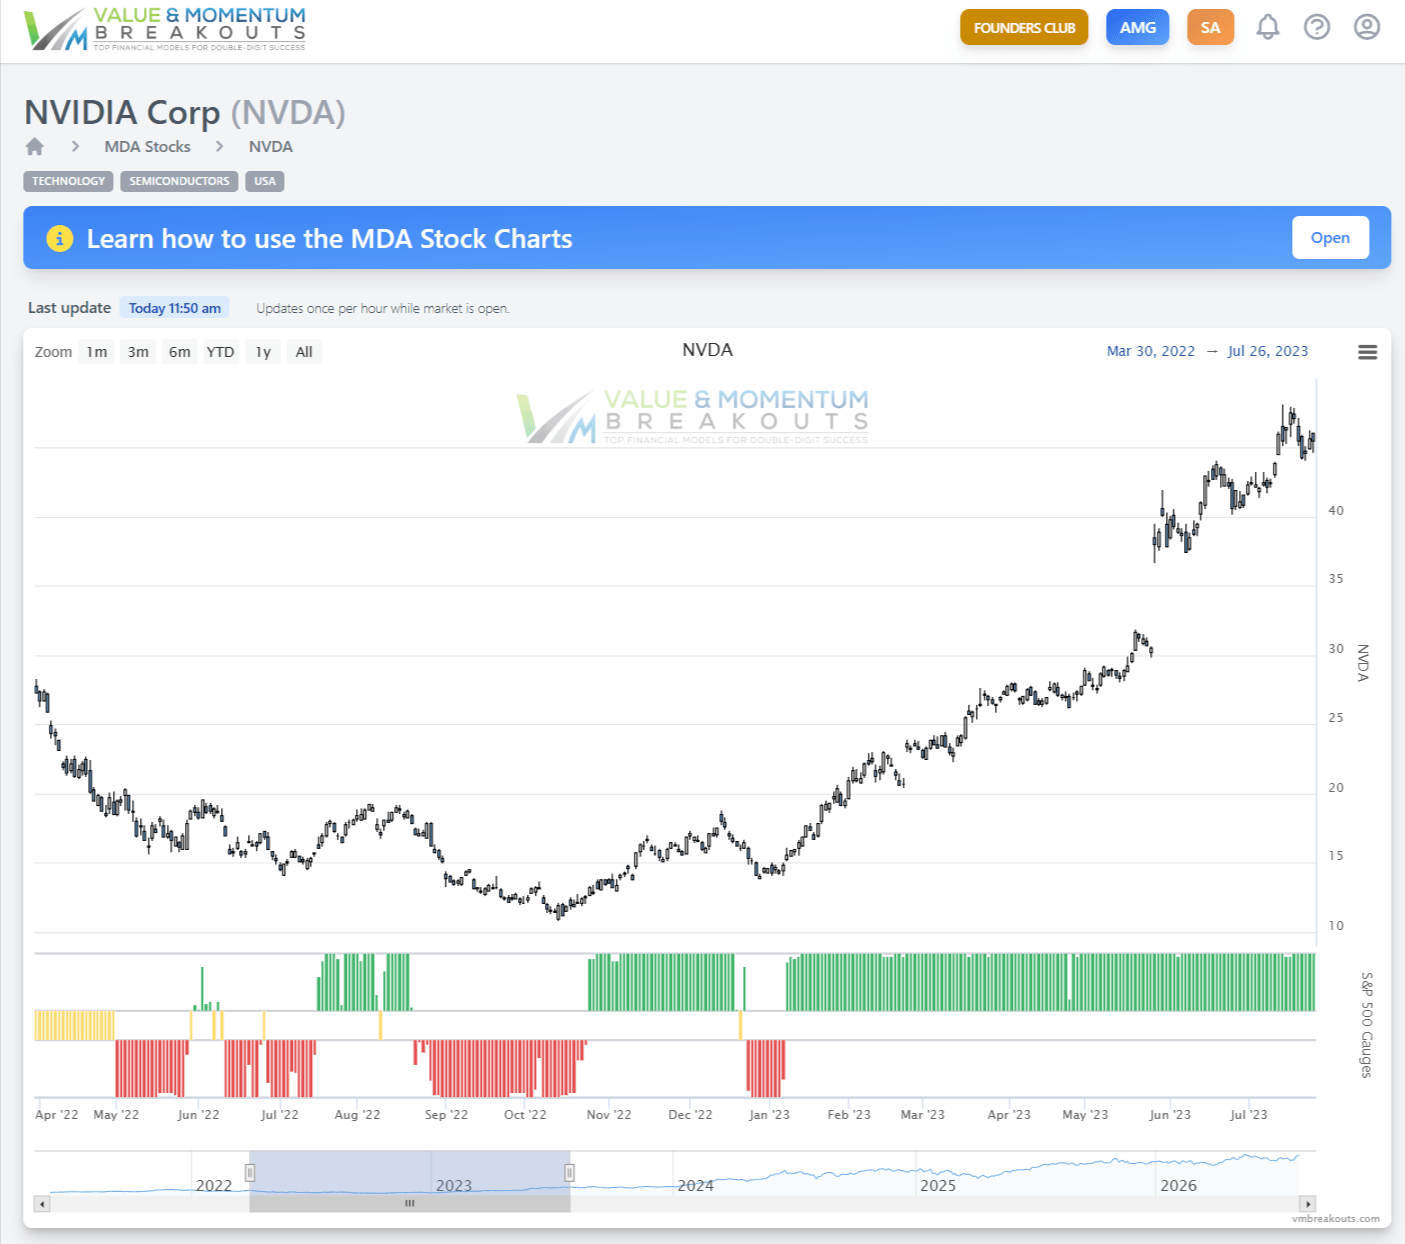
As you all know very well: It is much safer but not perfect — to capture the largest gains in NVIDIA and other good stocks using the MDA signals. Here is (NVDA) during the 2022 downturn to the July 2023 record recovery shown in the chart above.
Why don’t you use the SA Quant model to improve your returns?
This is another question that I receive, especially if the weekly breakout picks are performing poorly. Seeking Alpha has been very good to me as an investment group contributor on their website. I deliberately avoid critiques of other services and especially one to which I am a paid contributor in their investment groups. However, I am going to clearly answer why I don’t personally use the SA Quant model and unpack some of the performance concerns I have.
The first explanation is easy:
The only portfolio and stock models that I use are ones that I have personally tested and developed or I have adopted from peer-reviewed financial literature that have demonstrated significant evaluated out-performance. What I am sure you will find after reading many hundreds of financial journal articles is that the documented “massive” outperformance results of these studies will be couched in humble, understated language. These scholars will state with humility buried somewhere near the end, something like “this study shows risk-adjusted returns as high as 2.3% a year.” In the world of finance that is actually a meaningful statistical advantage producing large market-beating returns.
That world of scholarly testing and peer-evaluated claims is generally on the opposite spectrum from the Multibagger marketing world. However, the worlds have collided and most traders want big results, in big numbers, that are extremely clear and obvious. Under these pressures to be the best, the claims start to get stretched.
The second explanation is more complicated:
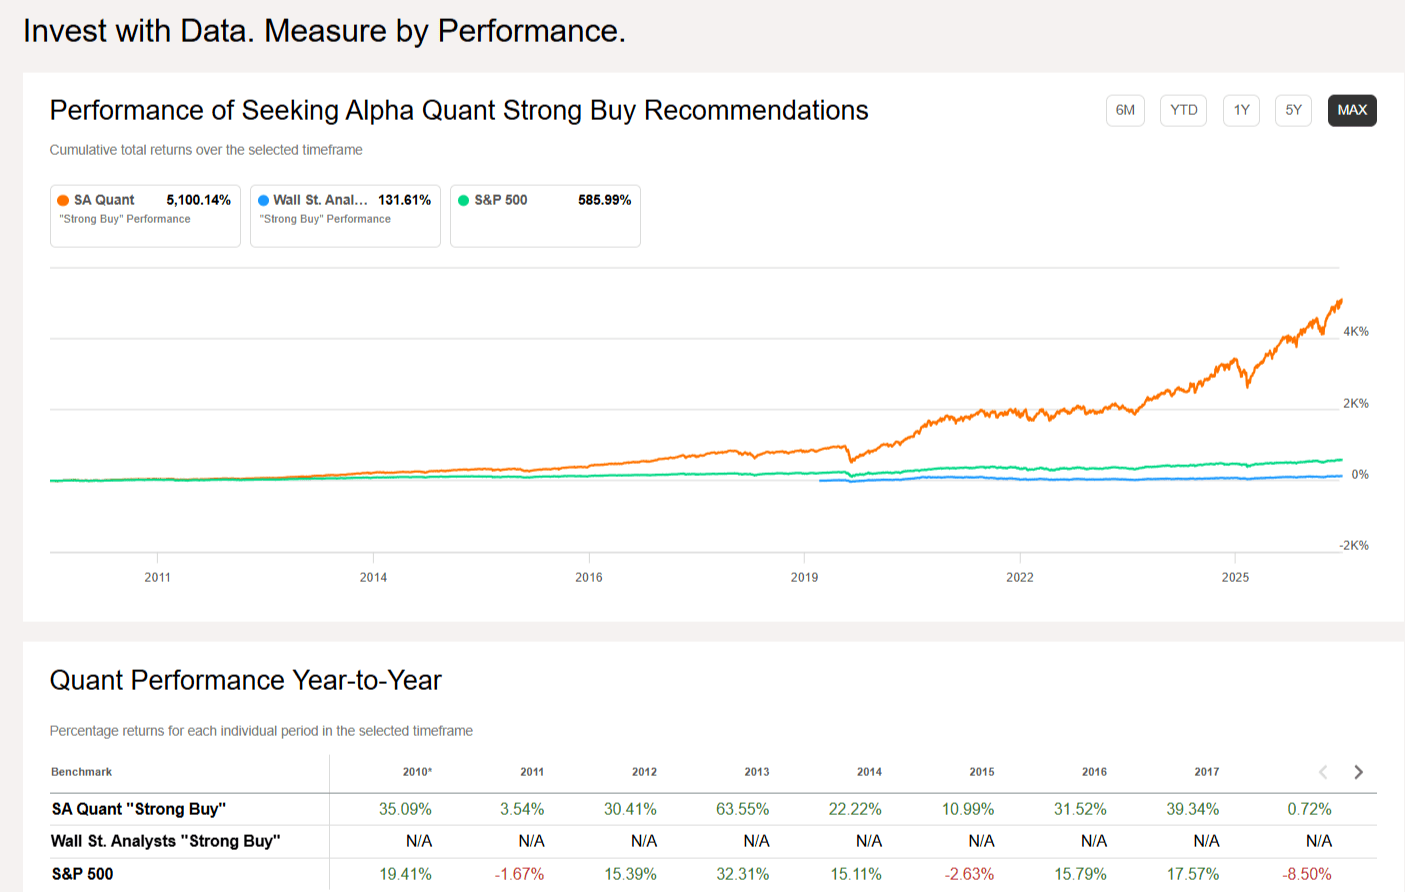
Initially I receive a comment or blog post or an honest question along the lines of, “Hey, the SA Quant portfolio is up +5,100% why can’t you keep up??”
This question actually goes back to when I was graciously invited by SA in 2017 to make all my posts and research portfolios into one of their Investment Group services as a paid contributor. Naturally, I was very excited to build out many more models and share many results I find highly beneficial. At that time, and years later, there was no SA Quant system on their platform. Then suddenly around 2021, I believe, this new feature arrived with tremendous results that competed directly with many investment services like my own.
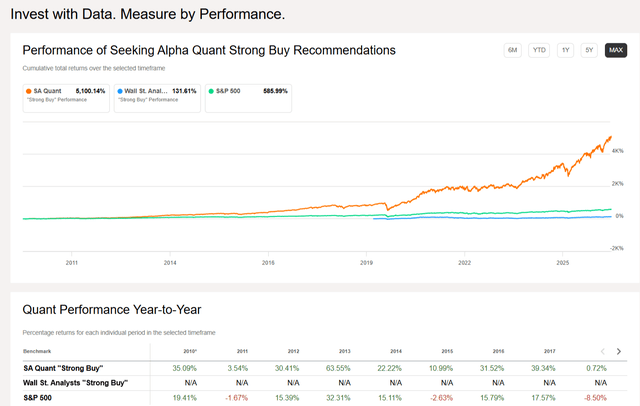
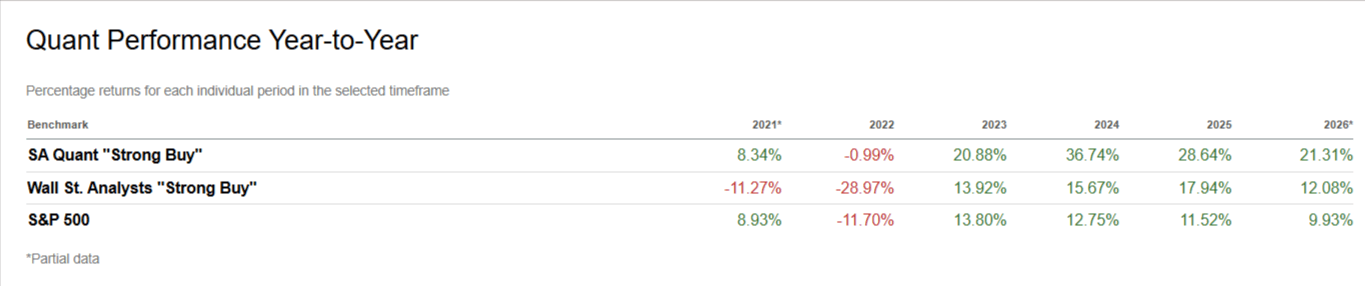
However, unlike my live forward testing, this new SA Quant model arrived with a prior multi-year track record. I could not review the prior annual portfolios, actual holdings, or historical trades. But I was certainly struck by the large reported gains now up to +5,100% current returns that headline the model. I don’t have any idea how much of the returns are simply backtested estimates, but I noticed that in 2021* it flags as a partial data year. It suggests to me that 2021 was the live start year and prior data may have been backtested or backfilled in some way.
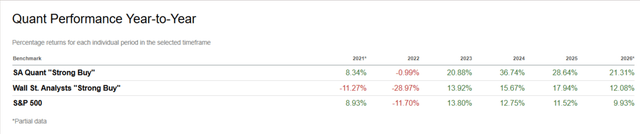
2021 was a reasonably challenging year for many portfolios and I do not know how partial the Quant returns were for 2021 to deliver +8.34% returns that year. I also do not know which Wall Street Analysts portfolios comprise the returns for the “Strong Buy” returns posted, but it doesn’t look like we want those returns anyway.
All I can do at this point is compare the posted results to actual long term portfolios by the years for which I have live forward returns data. These returns do not include adjustments from additional dividends in each portfolio, each year, that would further compound the returns. Perhaps neither does the SA Quant “Strong Buy” portfolio include dividends as well.
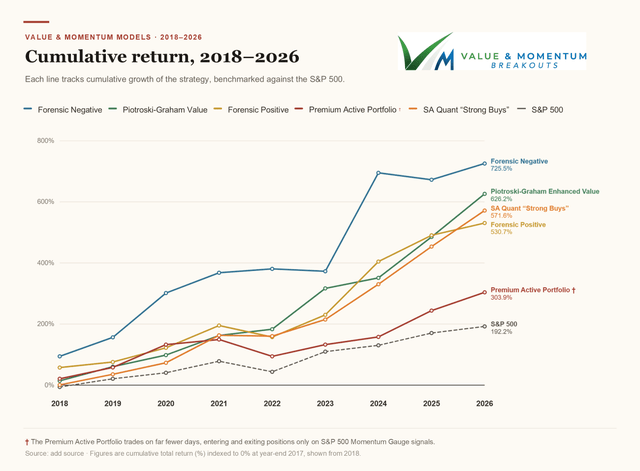
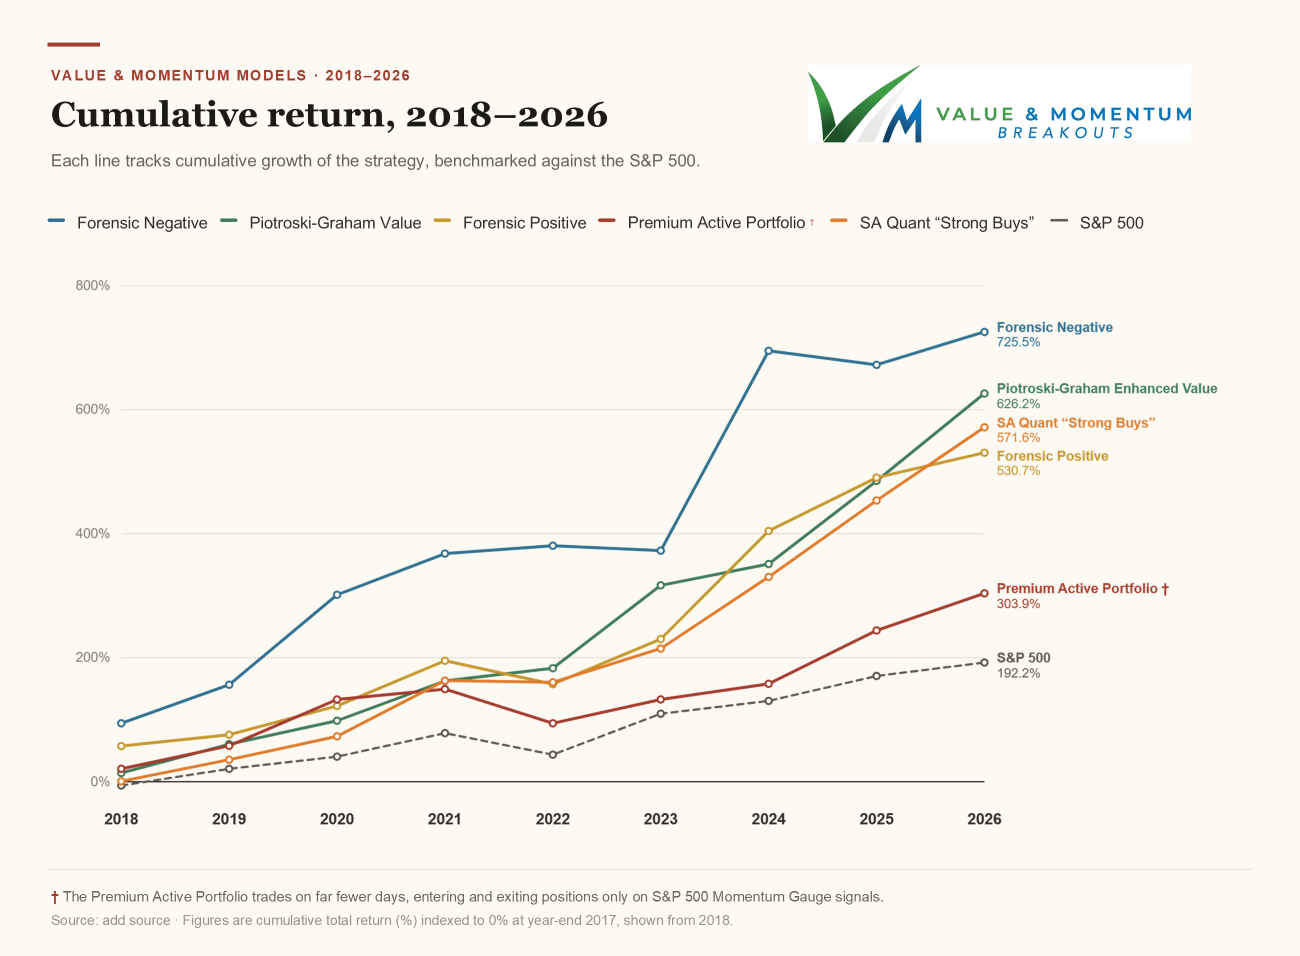
The cumulative results show that two of my long term buy/hold portfolios with fixed annual stock selections, Forensic Negative +725.5% and Piotroski-Graham +626.2% are currently outperforming SA Quant “Strong Buys” up +571.6% from their initial full year returns starting in 2018.
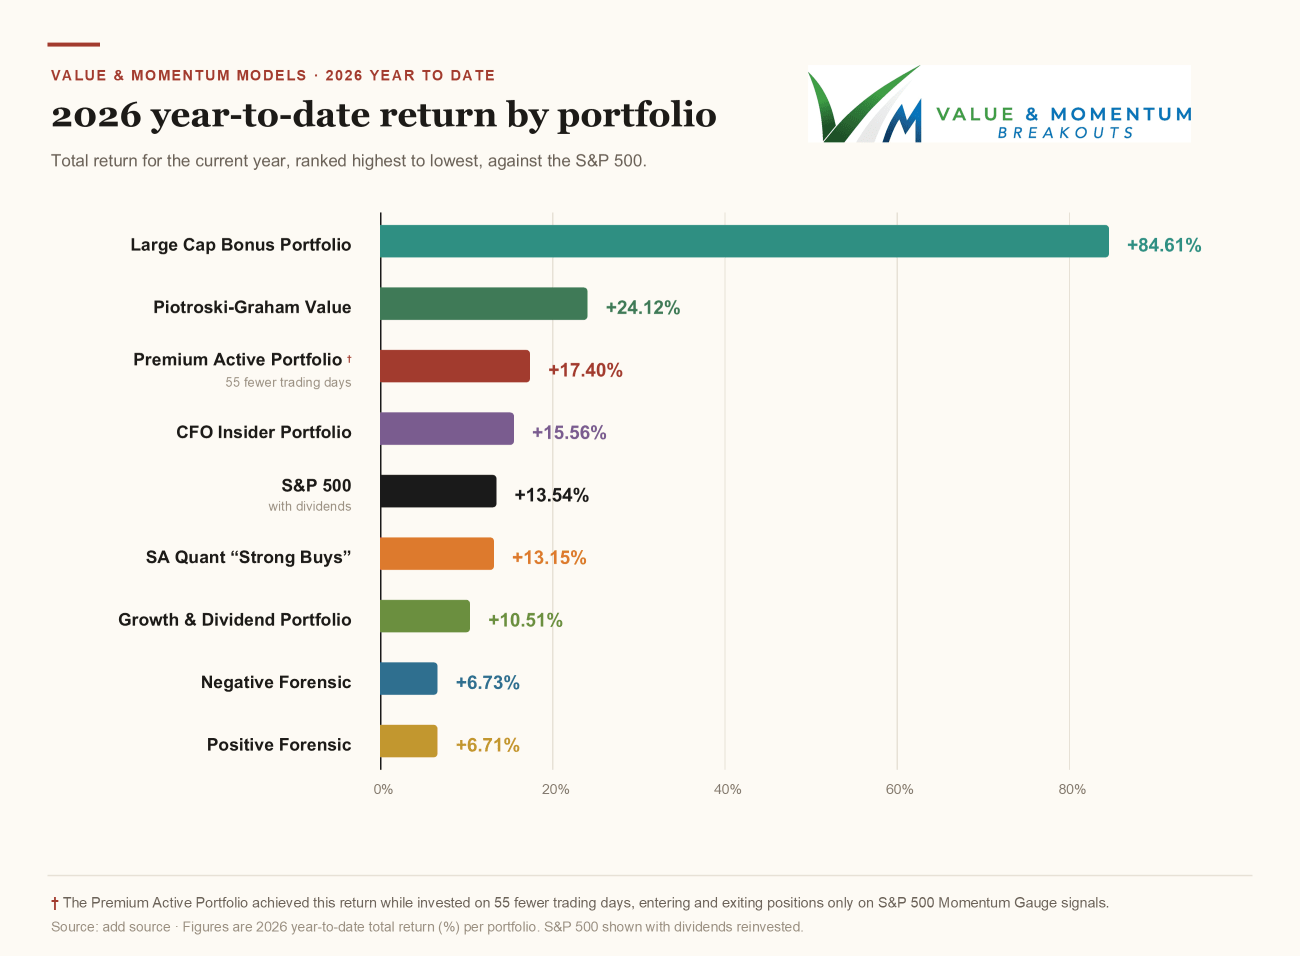
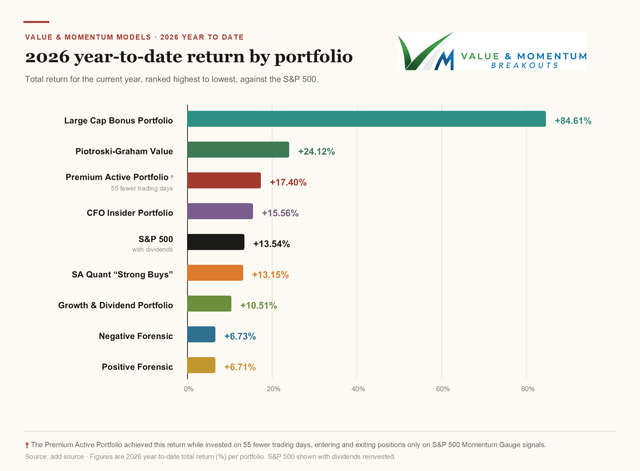
This year for the first time ever I added a SA Quant “Strong Buy” portfolio, a new CFO Insider portfolio, and the first Large Cap bonus portfolio from the start of 2026 and tracked them like new long term portfolios. The Large Cap bonus portfolios are ongoing weekly since 2020. The 2026 results are shown below through today. The SA Quant official returns are +21.3% YTD in the last update, compared to the fixed portfolio of strong buys selected at the start of the year.
The multi-year cumulative performance chart strongly suggests that my long term buy/hold portfolios are well on their way to over 5,000% returns in the coming years. But then it occurs to me that my equivalent “Strong Buys” stock selections are not the modeled value portfolios published for annual measurements, but the Weekly MDA Breakout picks. These MDA breakout picks measured since the day I arrived on SA in 2016 were essentially designed to test out my new high frequency “Strong Buy” breakout model.
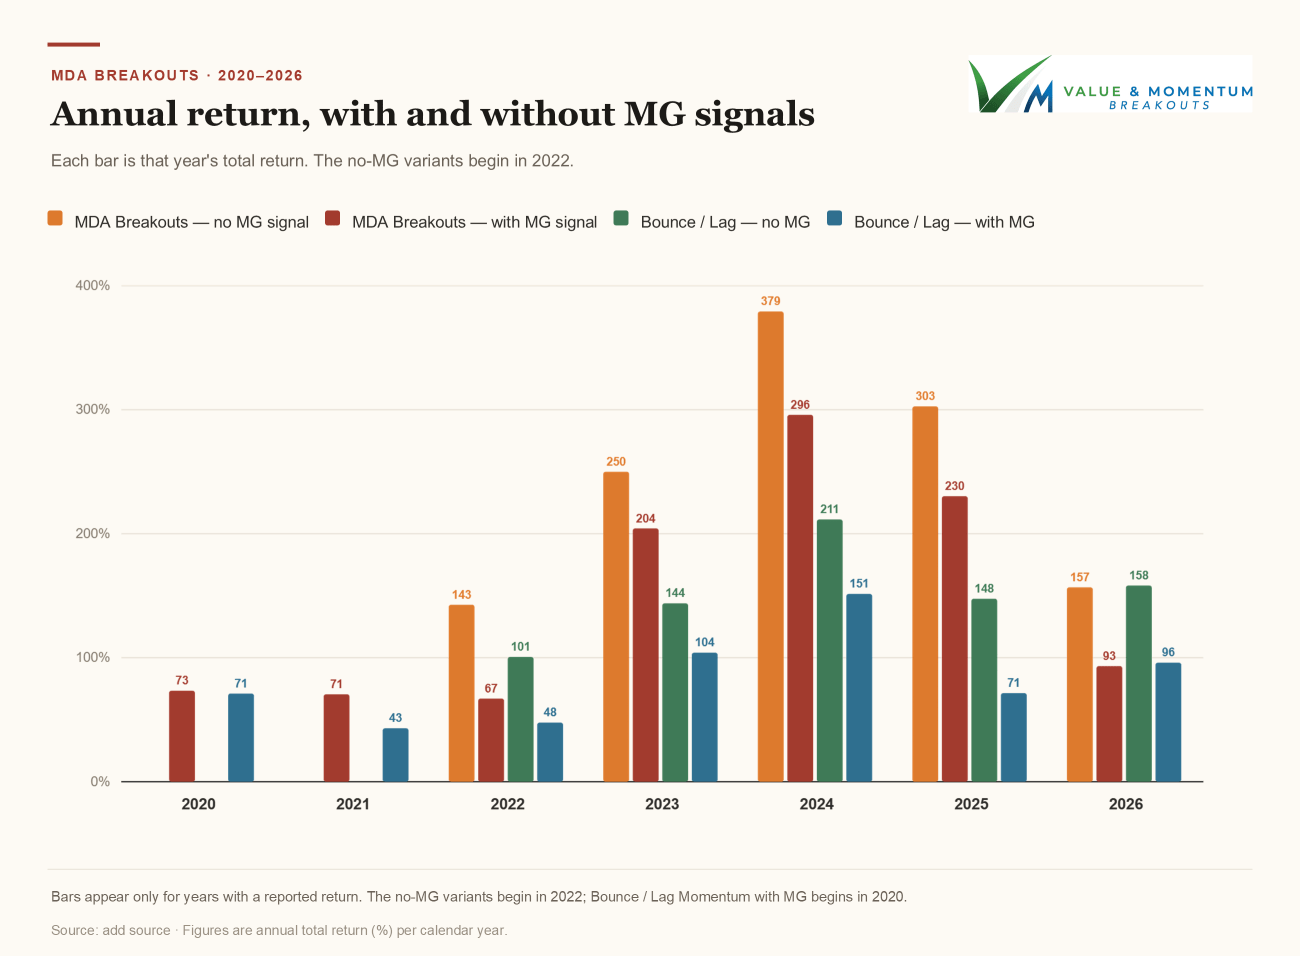
My published returns of average weekly cumulative returns by year with and without using the Market Gauge signals are shown below. The chart also includes Prof. Grant’s Bounce/Lag breakout model that for the first time since tracking began, is leading the MDA breakout selections on the average cumulative weekly measurements. Fortunately, we still have nearly 5 months remaining in the year for this test competition to continue.
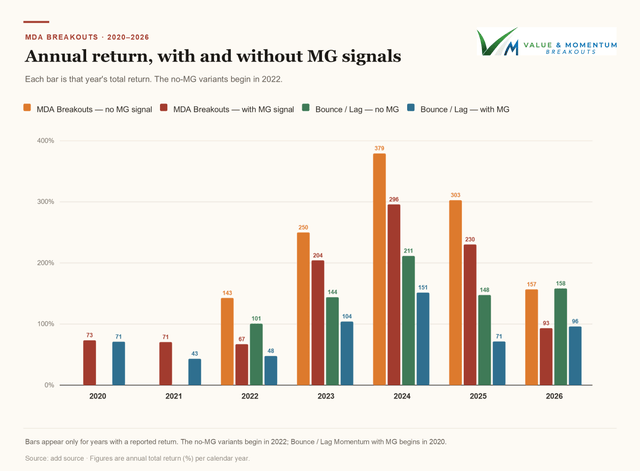
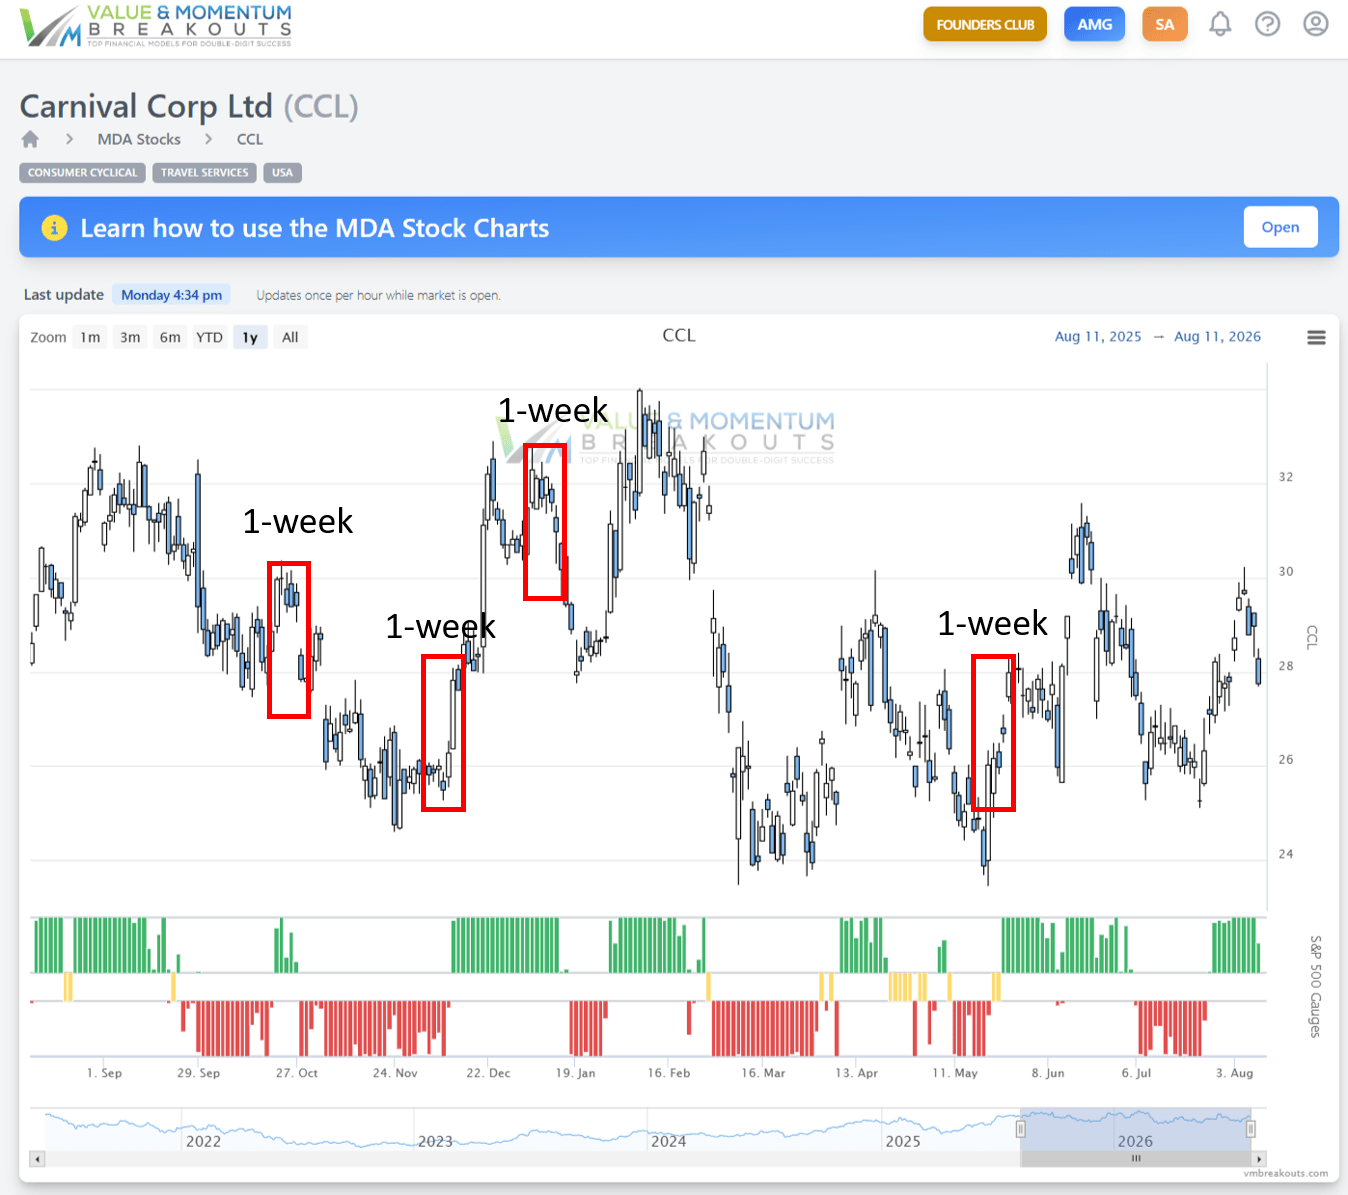
These are test returns returns adding average weekly returns together. Average weekly returns are based on the average of peak returns for a stock in an arbitrary 1-week measurement and the minimum returns are the returns at the end of the week ignoring all the signals, earnings, news, CEO resignations and downturns for the entire week.
Aren’t your Breakout returns exaggerated?
No, the MDA and Bounce-Lag weekly breakout returns are exactly what they claim to measure from the moment a stock is selected to the end of the fixed arbitrary 1-week measurement period. Do they match member expectations about what everyone thinks it measures? No, not always. In the Getting Started Investor Resource section and the FAQ article section 22 and other articles I explain exactly how and why the measurement started in 2016 to model my MDA dissertation results.
Now that I have automated MDA breakout signals there is no particular reason to continue the blind, fixed, 1-week arbitrary measurement model from 2016. Over the years members have asked me to change the date/time of the weekly MDA stock selections, the number of stocks released, and the way they want to see the returns artificially annualized. I am always happy to adjust and accommodate member requests. It does not change the reliability of the MDA breakout stocks or the value of using the live MDA signals to produce the best possible returns through conditional monitoring.
In fact, I submit that if I were to only measure the returns during positive Segment 6 (green) against the returns in negative Segment 2 (red) the returns of the MDA breakouts would be even more profitable than a fixed 1-week blind measurement.
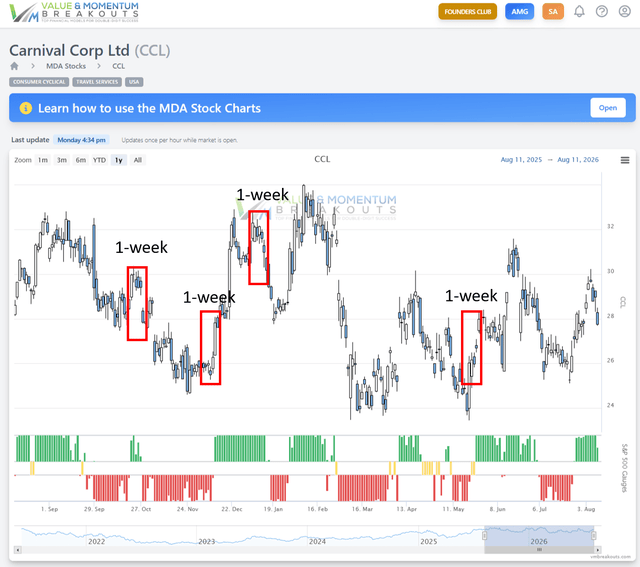
The point is that the average weekly return tracker from 2016 does not follow the new live MDA signals on a daily, hourly or 15 minute basis. It takes the average of the week, each and every week, and still shows a statistical advantage of buying a stock that begins the week in Segment 6 breakout conditions. We cannot know in advance how long a stock will stay in Segment 6, but we do know that momentum persists. Intuitively it is not about the length of the holding period, 1-week or 3-weeks, that matters most. What matters most is how long a stock stays in the positive signal across all the variables being measured live every minute for the best breakout conditions.
So what can we really expect?
Most investors have been told to plan on 8% or 10% annual returns for all their retirement targets. I will hand off this section to a respected voice outside of my service who explains many market concepts very well. Lance Roberts from Real Investment Advice, says that “Average returns are not normal — normal returns are extreme.”
Average returns are the “end of year” returns averaged across decades. Depending on where you start your averaging you can see that every year saw declines averaging over -13% on the S&P 500 from 1980. This means to see an average gain of around 10% on the S&P 500, you would have had to experience an average decline of -13% (and likely more than once) across the same time period.
Many investment services do not show this information, but rather focus your attention on only the cumulative appreciation of steep S&P 500 curve in a well stretched out chart.
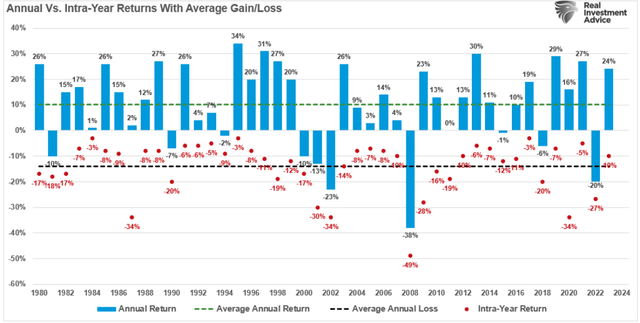
This is probably one of the most comprehensive and honesty views of the S&P 500 that investors should closely consider. Not surprisingly, in some years the average intra-year losses persist to the year-end measurement.
” The chart below compares the S&P 500 to annualized returns and the average of market returns since 1900. Over the last 125 years, the market has never produced a 10% return every single year; the average annual real return has been 7.33%. “
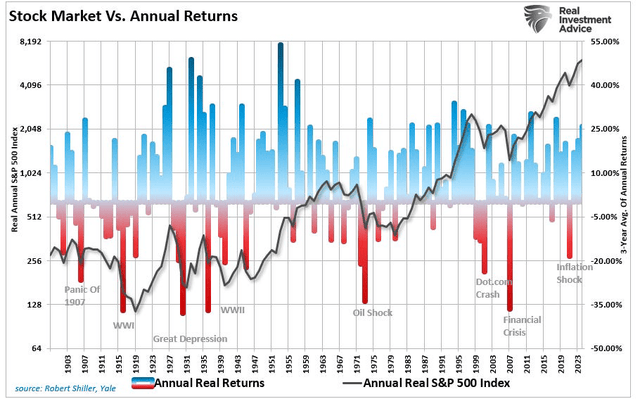
” The second point, and probably most important, is that YOU DIED long before you realized the long-term 100 year average rate of return. “
This article from Lance Roberts is one of the best treatments of what expectations we should really have going in to the market with large sums of retirement money:
Remember to keep every individual stock selection within the context of the markets, the sectors, using the gauges to increase your probabilities of catching strong momentum and avoiding major breakdowns:
- Positive Signals: A Majority Of Sector Gauges Go Positive For The First Time Since June
- The Three Largest Flows: Cracking The Hedge Fund Code – Part 3
Conclusion
I will conclude where I began. The financial investing world is full of hype and promises that set some enormously high expectations that are rarely achievable. In this article I set out to make some additional clarifications and in a rare, uncomfortable step I made some critiques of other services’ performance marketing.
Competition in the financial world is intense and drives some institutions to manipulate or exaggerate outcomes. Performance charts are often stretched, chart axis may not start at zero, returns are extrapolated into the future, and performance data are favorably backtested for years to show enormous current returns. Stay skeptical, test the models. Remember also to keep the rules about Market, Sector, and individual stock momentum fresh in your mind. Everyone is looking for a performance advantage. Some are using marketing to hype an edge that is not meaningfully helpful and could be dangerous. I am glad to help on every step of your investing journey so do not hesitate to reach out to me with your doubts and concerns!
All the best in your trading decisions,
J. D. Henning, Ph.D.