Summary
- The model for markets as driven by three dominant flows: Fed policy, corporate buybacks, and fund flows, each shaping price action beyond fundamentals.
- Fed liquidity, buyback activity, and fund flows collectively override company-specific news, with interest rates and risk appetite as key underlying drivers.
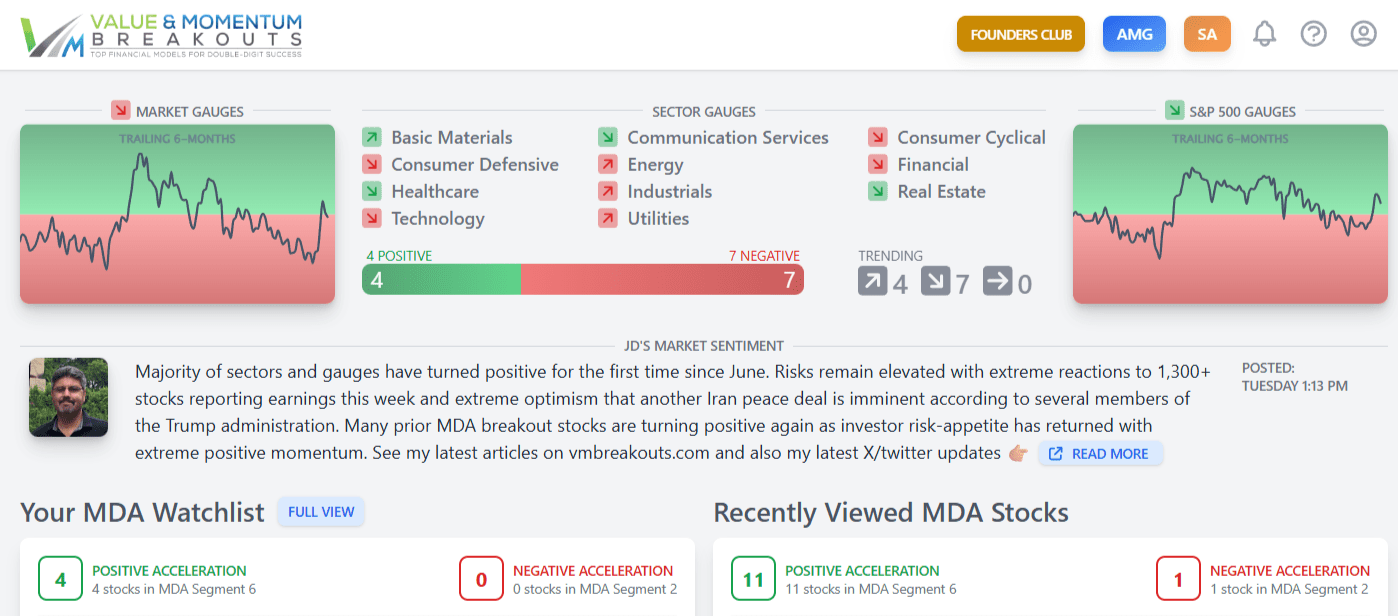
- The Momentum Gauge and MDA classifier measure the net effect of these flows, providing early signals ahead of headline indices.
- Risk management hinges on monitoring these macro flows; when they turn, even strong stocks may not perform without supportive money movement.
- This article also represents part of Chapter 16 in a first draft of my new book building on over 2,000 articles published exclusively for members.
This article builds on prior shared research for members in the series called “Cracking the Hedge Fund Code” that I wrote in 2019 and 2021. It also shares a first draft from Chapter 16 of my new book that is yet to be named and published. Member input and suggestions are always highly valued!
I share this information again now as we journey through Week 32 of 2026 with over 1,300 companies reporting earnings and severe chop of Segment 4 momentum cycle besets us. Sectors are sharply divided, Magnificent 7 stocks are sharply divided, industries in the Technology sector are sharply divided between Hardware / Software, between AI and IT.
Sometimes in choppy markets it is valuable to take a step back and look at some of the macro forces that are impacting the markets, just like the Big Money managers in hedge funds do every day.
Chapter 16. The Three Largest Flows
The hedge fund research in the last chapter points at something I have circled for years and want to set down plainly here, because it sits at the center of how I read markets. Most investors are taught a simple story. A stock goes up when the company does well, and it goes down when the company does poorly. Earnings and guidance are the whole game. That story is not wrong, exactly. It is just far too small. After nearly a decade of live forward testing, and thirty years of trading, I am convinced the market is usually looking at more than fundamentals and guidance. A great deal of the time the tape is being moved by something larger, and that something is the flow of money itself.
I model the market as money in motion. Prices do not rise exclusively because a spreadsheet says a company is worth more. Prices rise when more money is trying to buy than to sell, full stop. So the real question for a trader is not only whether a company is good, but where the money is going. And when you follow that question up the river to its source, you find that three flows do most of the heavy lifting:
Federal Reserve policy, corporate buybacks, and the great tides of fund flows. Underneath all three run the deeper currents that switch them on and off, interest rates, the carry trade, and the market’s appetite for risk. This chapter takes each of them apart. It will not turn you into a macroeconomist, and it is not meant to. It is meant to show you the forces the gauges are quietly measuring, so that when one of them turns you understand what you are seeing.
The First Flow: Federal Reserve Policy
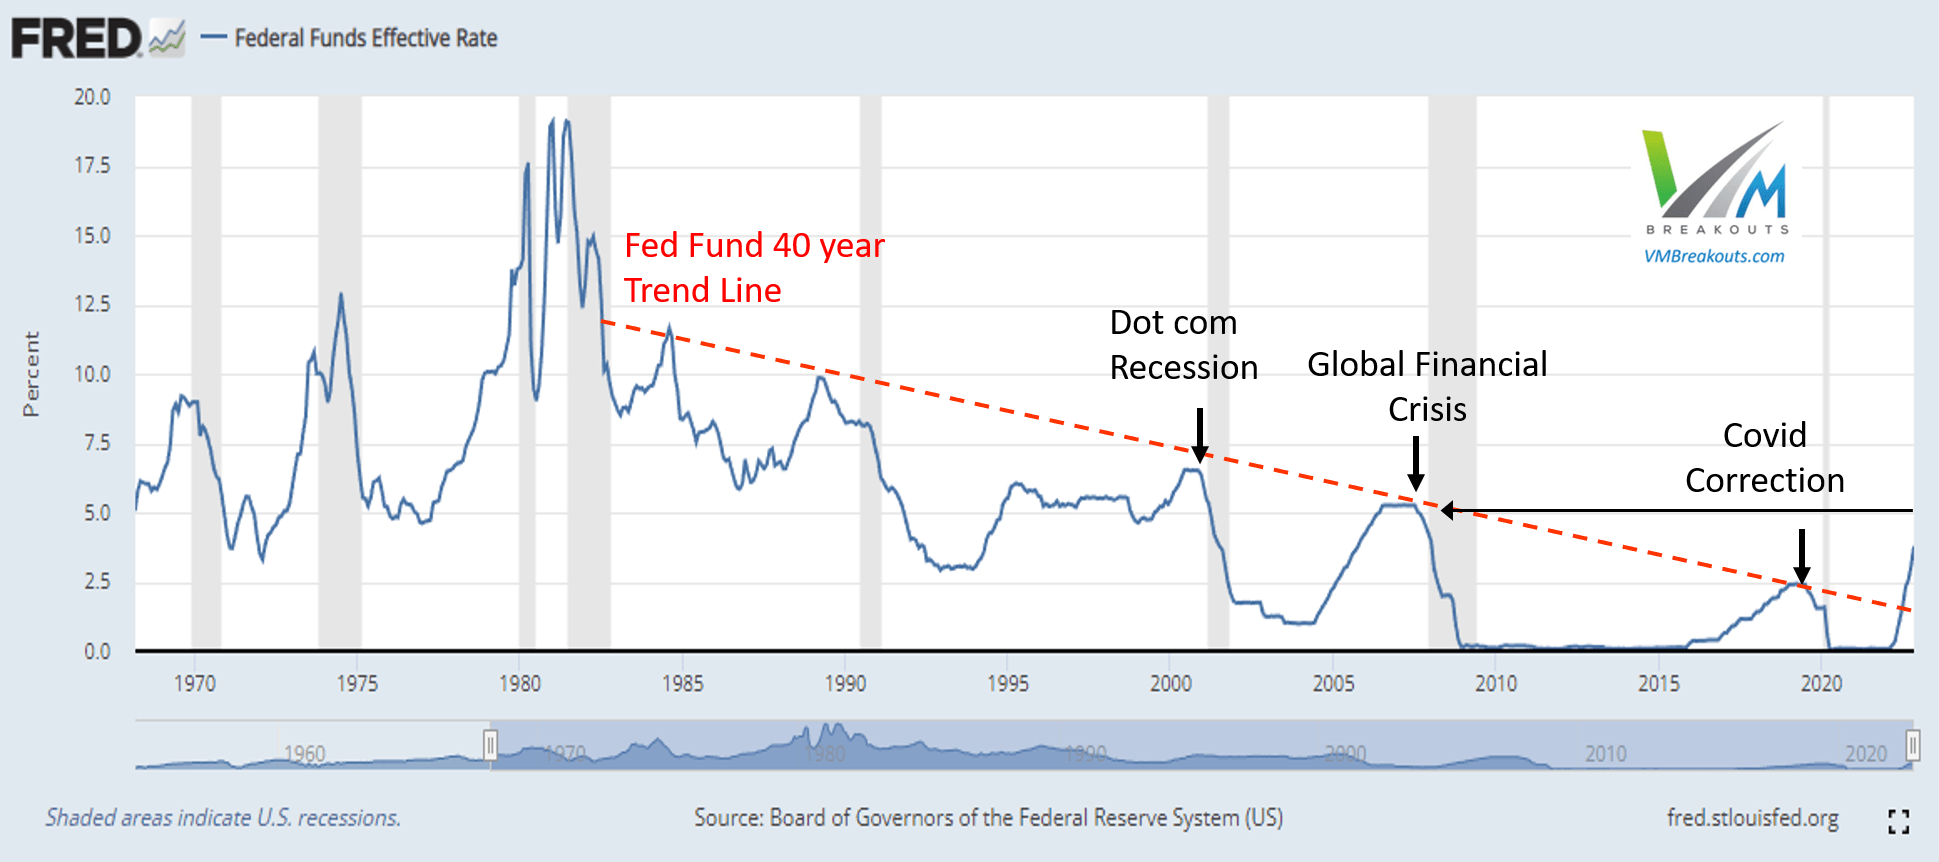
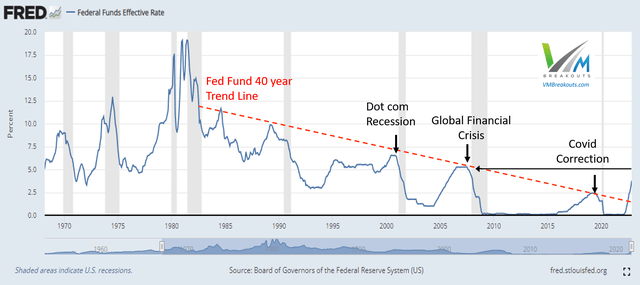
Start with the largest tap of all. The Federal Reserve does not buy your favorite stock, and it never comments on any company’s earnings. What it controls is the quantity of money in the financial system and the price of borrowing it, and by moving those two levers it moves everything else.
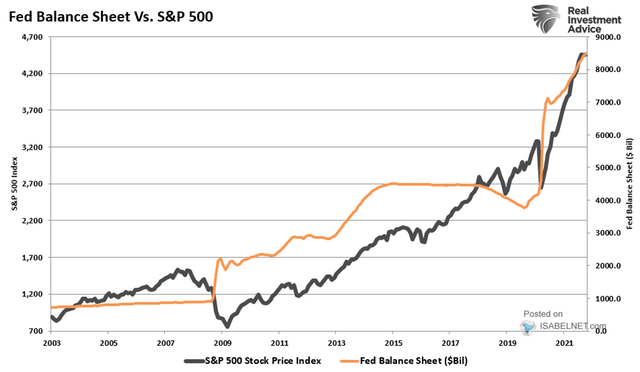
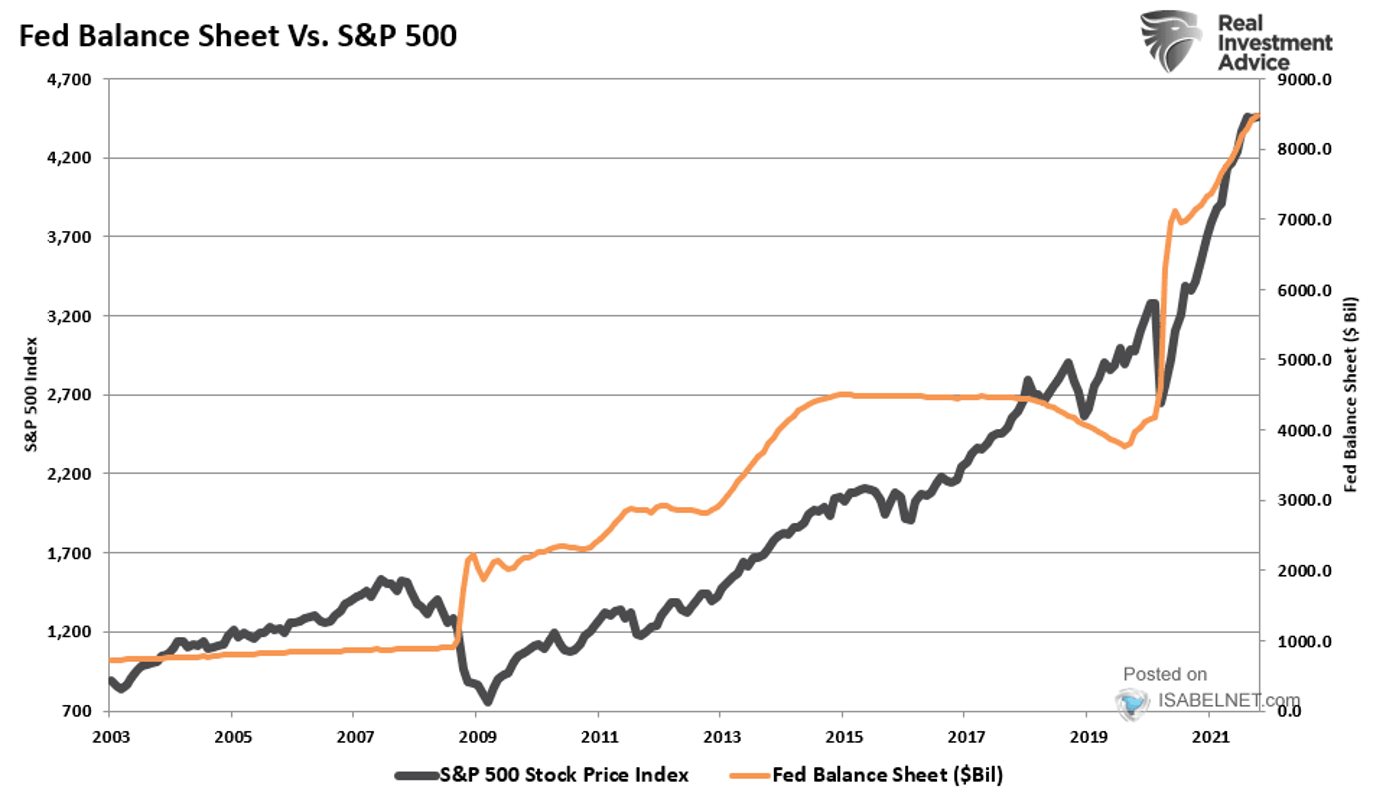
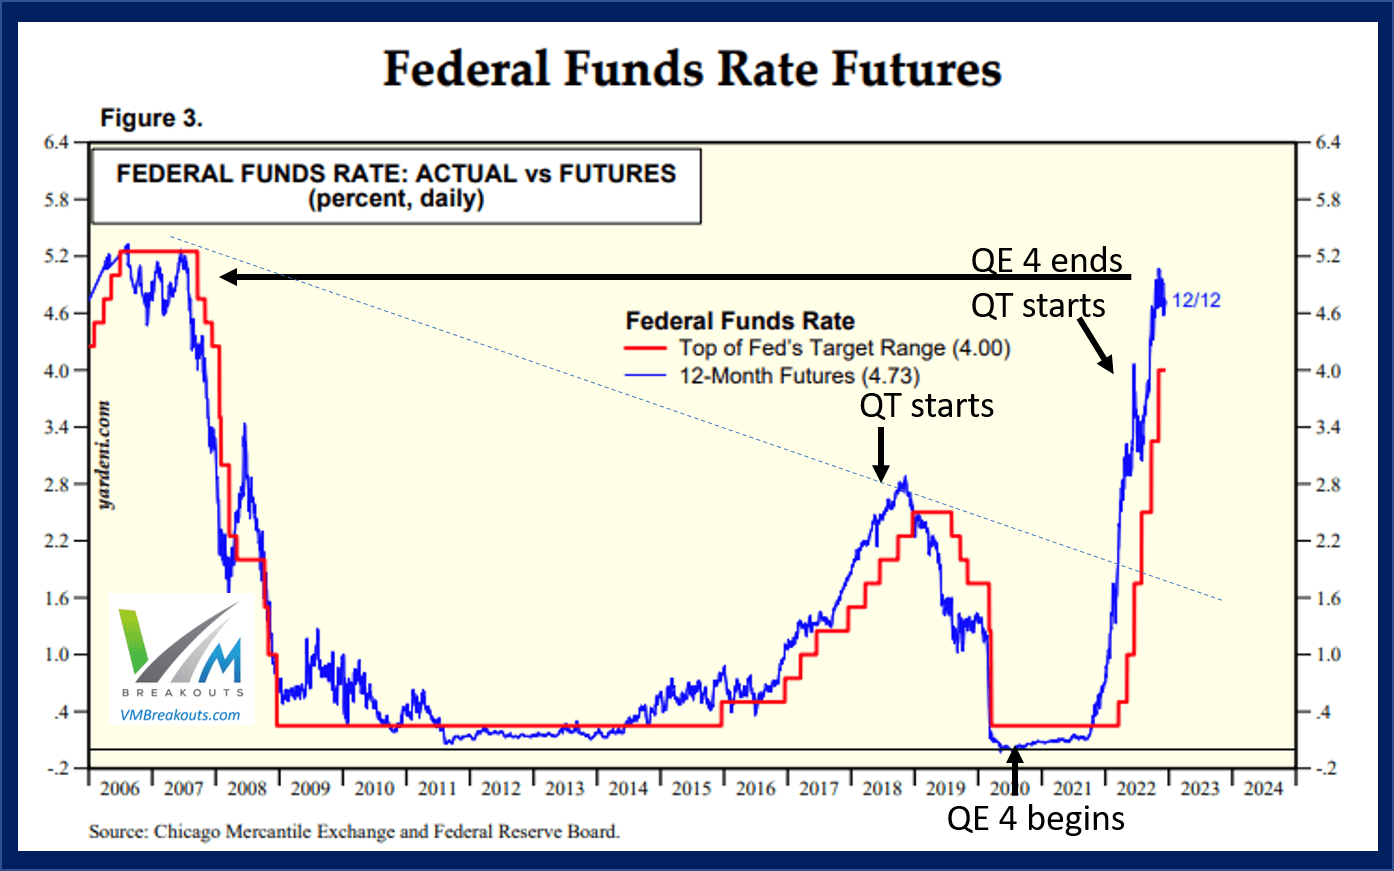
When the Fed wants to support the economy, it creates money and uses it to buy bonds, a program the world came to know as quantitative easing, or QE. Two things happen at once. The system fills with new cash that has to go somewhere, and the return on safe assets like Treasuries is pushed down, which nudges that cash toward riskier assets like stocks in search of a better return. This is the rising tide that lifts nearly every boat, seaworthy or not. When the Fed reverses course and drains money back out, quantitative tightening, the tide runs the other way. Cash leaves the system, safe yields rise and compete with stocks, and even good companies find the water falling out from under them.
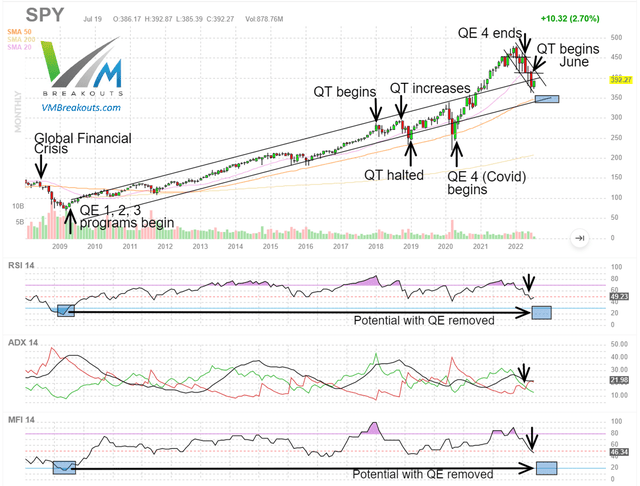
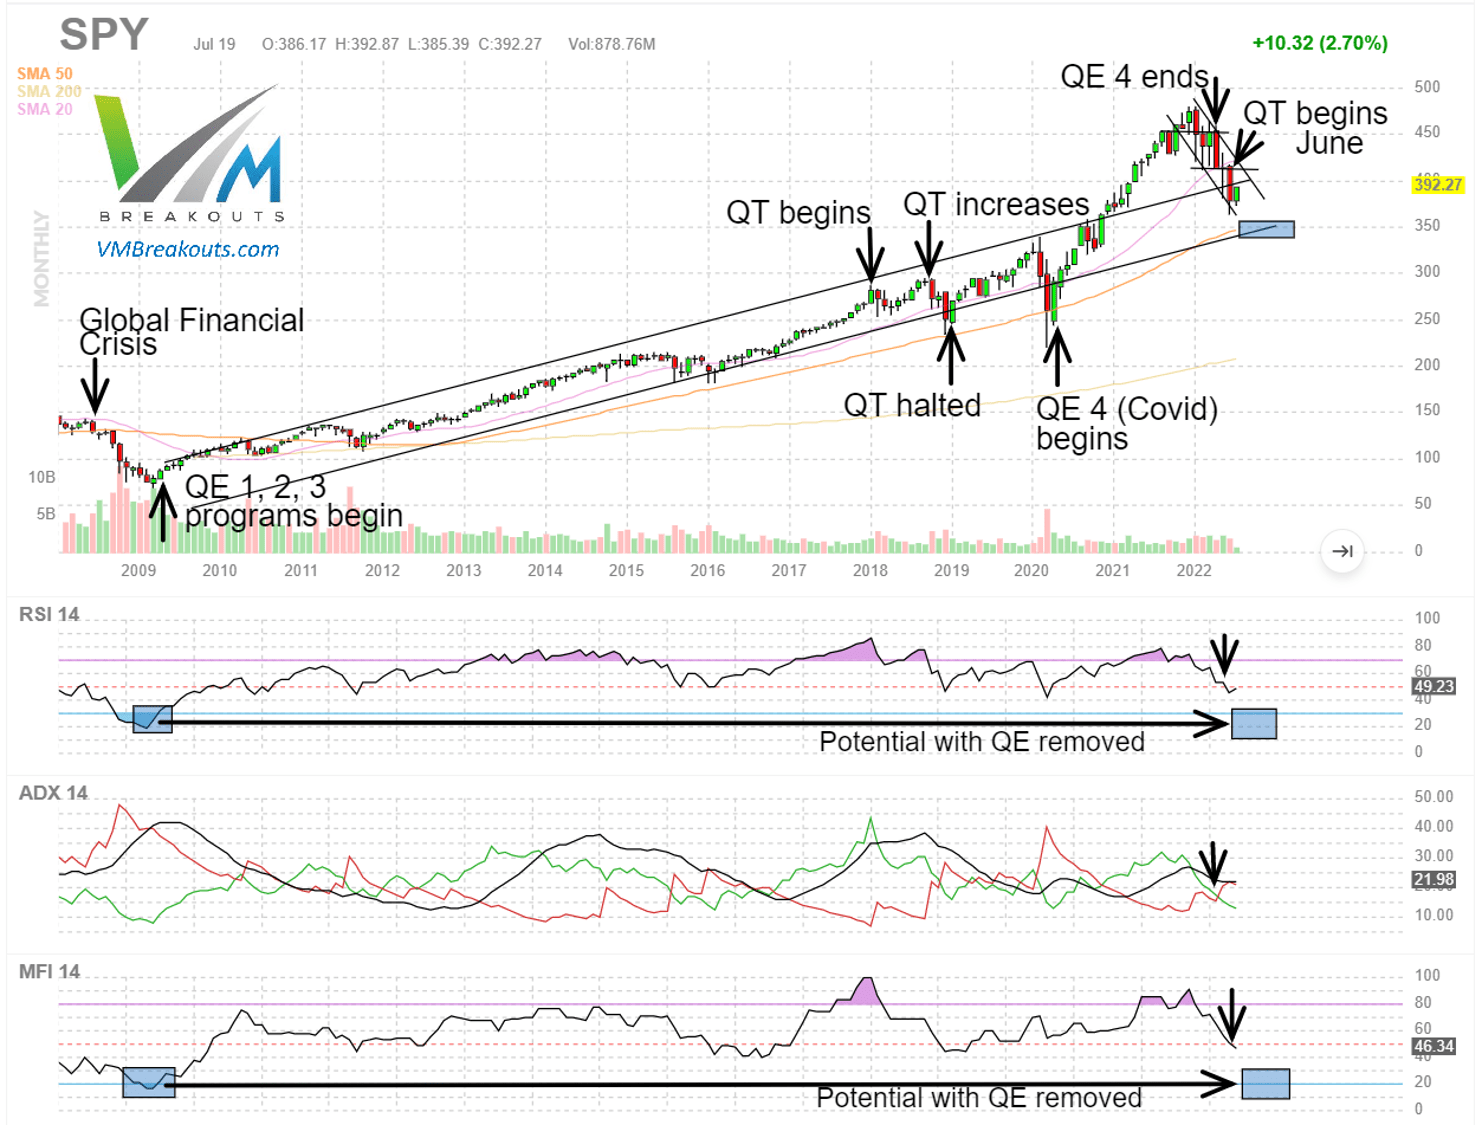
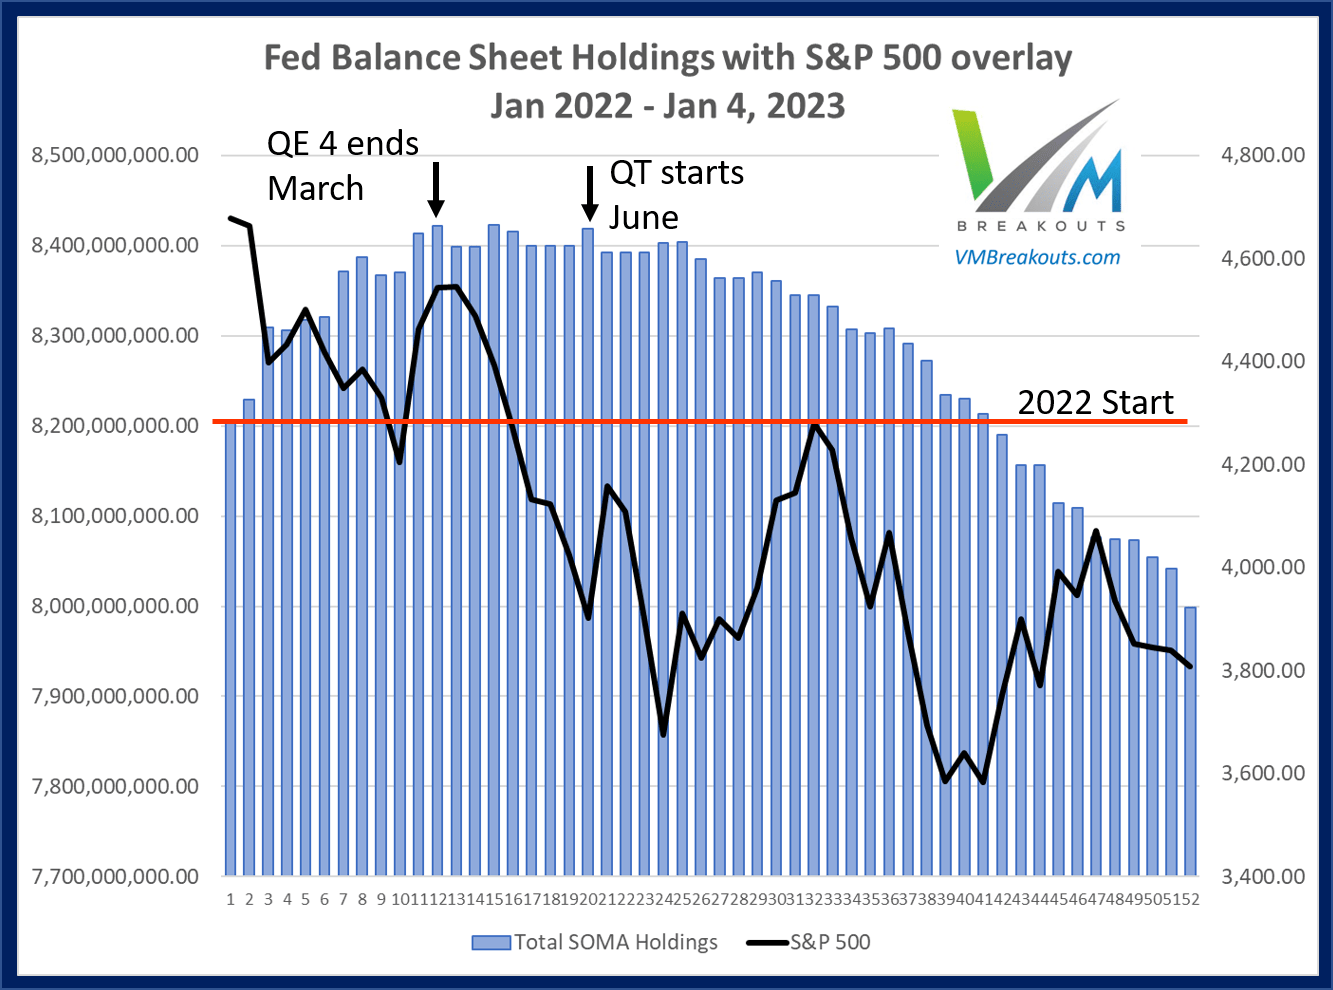
You have already watched this force at work across the live record. The two decades behind the chart in Chapter 2 are, at the core, a story of Fed liquidity. The crisis response of 2008 and the QE programs that followed, the quantitative tightening of 2018 that handed the gauges their first real correction to flag, the emergency flood of QE4 in March 2020 that turned the market so fast the recovery began almost the instant the money arrived, and the tightening of 2022 that produced the worst year since 2008. In each case the gauges were not reading the Fed’s statement. They were reading the footprint the Fed’s money left in the breadth of the market, more stocks accelerating into Segment 6 when the tide came in, more collapsing into Segment 2 when it went out. Liquidity is the tide beneath the momentum, and the Fed is the moon that moves it.
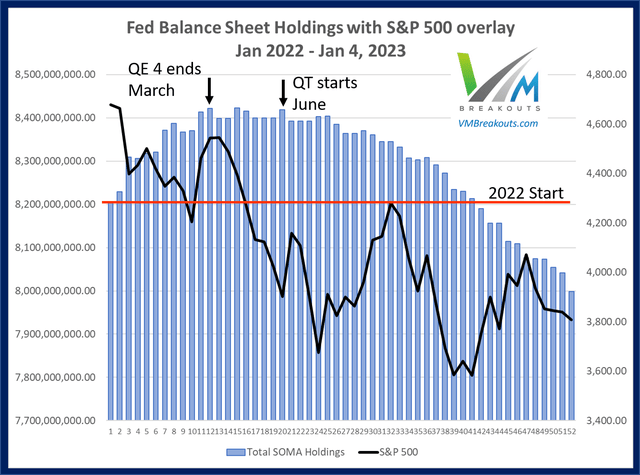
The practical point is not that you should try to forecast the Fed. Better economists than I have gone broke doing that. The point is that Fed policy is a force large enough to override any fundamental picture, and the gauges will feel it turn before the headlines explain it.
The Second Flow: Corporate Buybacks
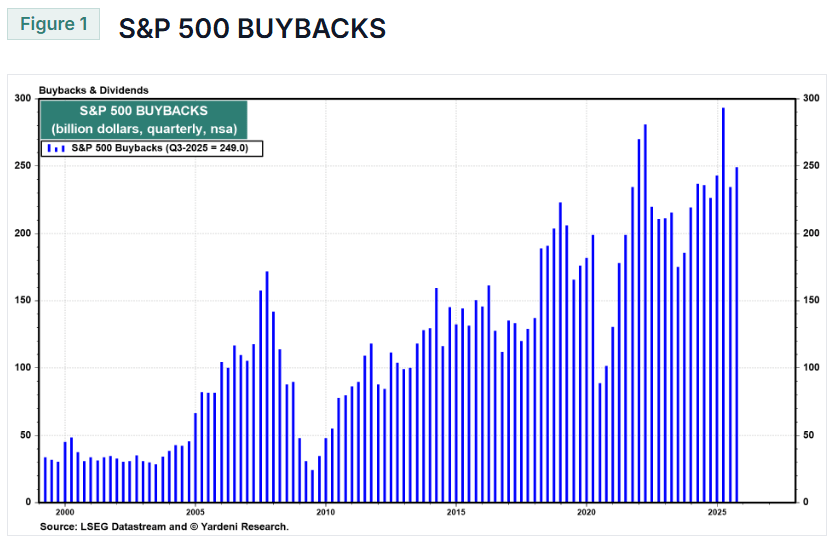
The second flow surprises people, because it comes from inside the companies themselves. When a corporation generates more cash than it needs, one of the things it can do is buy back its own shares in the open market. For much of the past decade, corporate buybacks have been one of the single largest sources of demand for US stocks, in some years larger than the buying from all individual investors and pension funds combined.
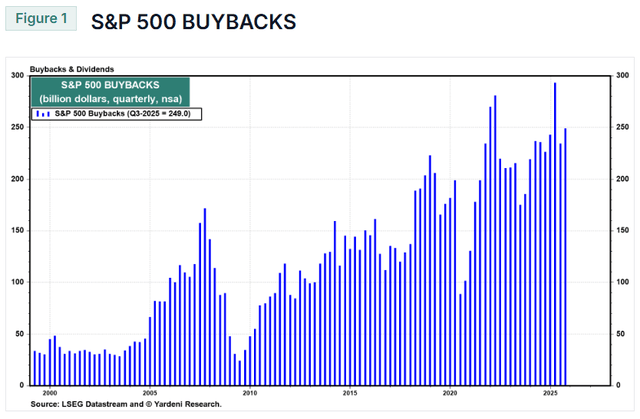
Think about what that means mechanically. A buyback is a buyer who shows up quarter after quarter, in size, and who does not care what the stock’s valuation is or what a chart looks like. It is price-insensitive, persistent demand, a steady bid sitting underneath the market that has nothing to do with this week’s guidance. It also shrinks the number of shares outstanding, so the same amount of earnings is spread over fewer pieces, which lifts earnings per share even if the underlying business is flat. A rising stock and a shrinking share count can look like a healthy company when what you are really watching is a company spending cash to support its own price.
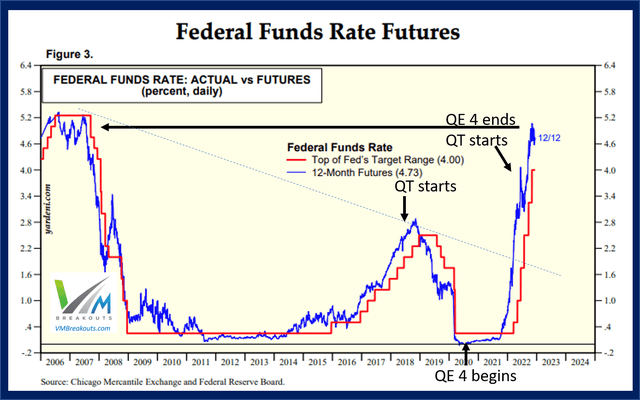
Two details make buybacks worth watching closely. First, they are financed most easily when money is cheap, which chains them directly to interest rates. Low rates make it attractive for companies to borrow and buy their own shares; rising rates make that math worse and can quietly remove a major buyer from the market.
Second, companies are generally restricted from buying their shares in the weeks just before they report earnings, a period called a blackout window. When that steady bid steps away, the market can wobble for reasons that have nothing to do with news, and then steady itself again when buybacks resume. If you have ever seen the market soften into an earnings season and firm up afterward for no obvious reason, you may have been watching the buyback bid switch off and back on.
The Third Flow: Fund Flows
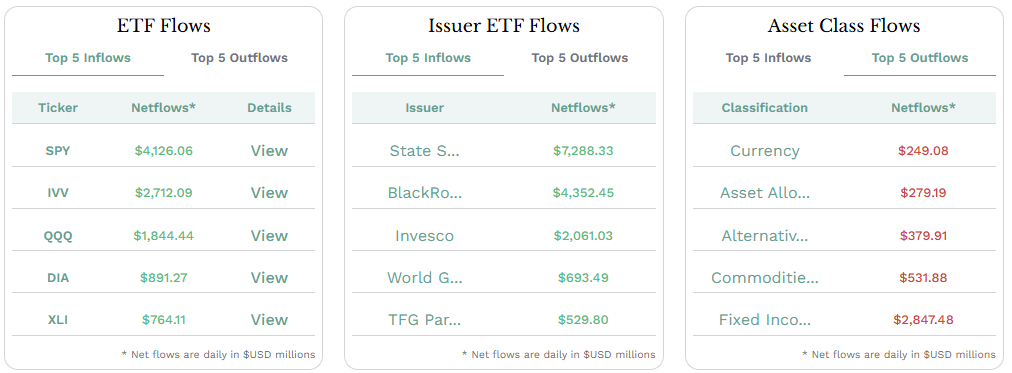
The third flow is the broadest, and it is the one that has grown the most in my lifetime. Fund flows are the rivers of money moving into and out of investment funds of every kind, and they buy and sell the market for reasons that often have nothing to do with any individual company.
Part of this river is slow and mechanical. Every paycheck, retirement contributions pour into index funds that must buy the whole market in fixed proportions, regardless of price. When indexes rebalance, or when a stock is added to or removed from a major index, enormous mechanical trades follow, again with no view on value. Exchange-traded funds create and redeem shares in baskets, moving whole sectors at once. None of this money is asking whether a company beat its guidance. It is simply flowing according to rules and schedules.
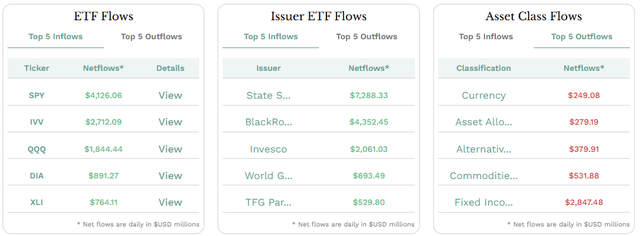
The faster part of the river is the institutional and hedge fund money I described in the last chapter. This flow is sharper, better informed, and quicker to move, and the research by Cao and his colleagues is a reminder that it carries real information. When large, sophisticated pools of capital begin accumulating a particular profile of stock, that accumulation drives prices, and it tends to draw more money behind it. Flows, in other words, can be self-reinforcing. Money moving into an asset attracts more money, which is momentum in its purest form, the herd behavior that sits underneath the whole price momentum anomaly this series is built on.
The Currents Beneath: Rates, the Carry Trade, and Risk Appetite
The three flows do not operate on their own. They answer to deeper currents, and understanding those currents is what lets you see why the flows sometimes all turn at once.
The master current is the interest rate, the price of money itself. Rates sit underneath all three flows at the same time. They set the Fed’s whole posture. They decide whether buybacks are cheap or costly to finance. And they steer fund flows back and forth between stocks and bonds, because when safe bonds pay very little, money crowds into stocks, and when bonds begin to pay a real return, some of that money goes home. A great deal of what looks like a stock-market story is really an interest-rate story wearing a costume.
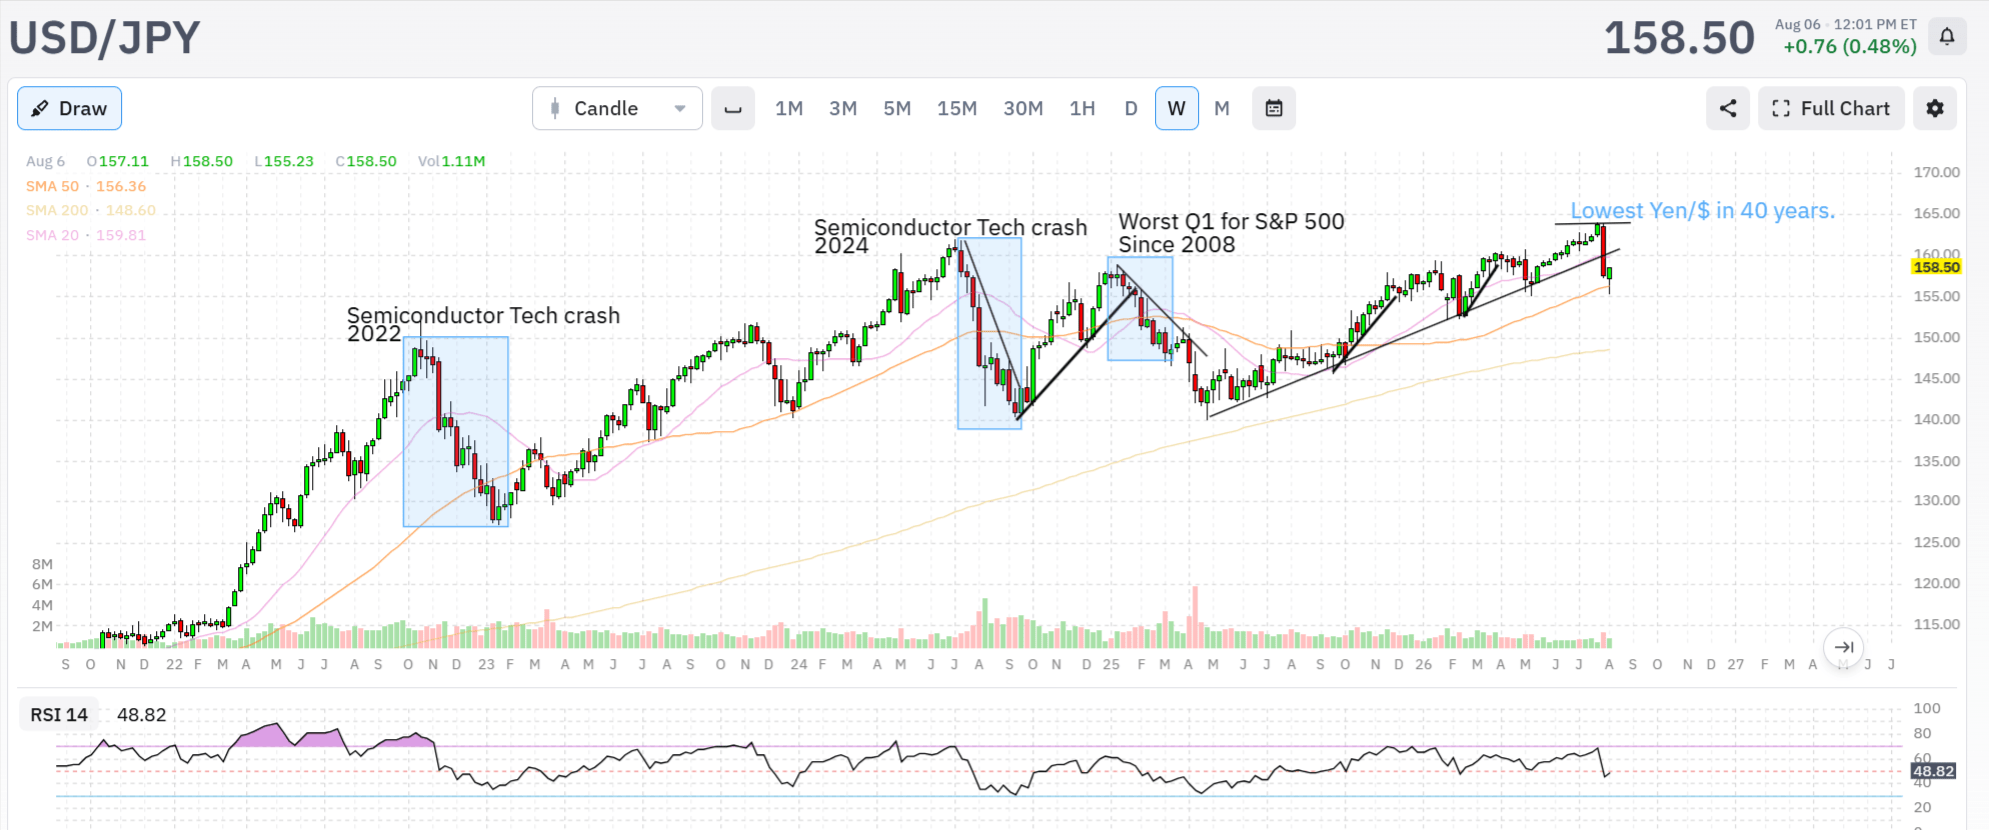
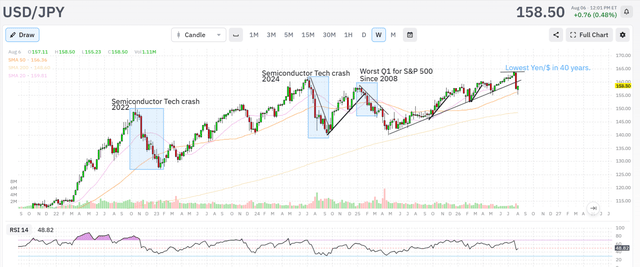
Riding on top of rates is the carry trade, one of the oldest maneuvers in finance. The idea is simple: borrow money where it is cheap and put it to work where it earns more. When funding is cheap, investors borrow heavily and pour the proceeds into riskier assets, and that borrowed money amplifies every one of the three flows I have described. The catch is what happens when the trade reverses. A carry trade is leverage, and leverage unwinds violently. When the cost of borrowing jumps, or when fear rises, everyone tries to sell the risky assets and repay the cheap loans at the same moment, and because so many are doing the same thing, seemingly unrelated markets fall together. A carry unwind is one of the clearest examples of why the market can drop hard for reasons that have nothing to do with any company’s fundamentals.
And the switch over the entire machine is risk appetite, the market’s collective willingness to hold risk at all. Risk appetite is what turns the flows on and off. When confidence is high, Fed liquidity, buyback cash, and fund flows all point into stocks, and the carry trade stretches further and further. When fear takes hold, the same forces reverse in unison, and no fundamental picture is strong enough to stand in front of them. Risk appetite is not a number on a screen. It is a mood, and it is exactly the human, behavioral force that makes momentum persist and that no efficient-market equation has ever fully tamed.
Reading the Flows Without Predicting Them
Here is where the method comes back in, and where I want to be careful, because I am not asking you to become a macro forecaster. I cannot reliably predict the Fed’s next move, the size of next quarter’s buybacks, or the day a carry trade will snap, and neither can anyone selling you a newsletter that claims otherwise. The genius of the gauge approach is that it does not require those predictions. It measures the footprint the flows leave behind.
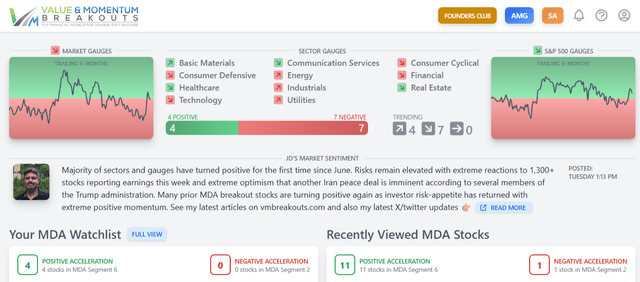
Every one of these flows, when it moves, shows up in the same place: the breadth of the market. When money floods in from Fed easing, from buybacks, from fund inflows, more and more stocks accelerate into the extreme positive condition of Segment 6, and the green line climbs. When the flows drain, stocks collapse into the extreme negative condition of Segment 2, and the red line takes command. The Momentum Gauge is, in a real sense, a flow meter. It does not know or care whether today’s tide is coming from the Fed or from buybacks or from a hedge fund rotation. It simply counts the result across thousands of stocks and tells you which way the net money is running. That is why a breadth instrument can warn you before the headline index does. Breadth feels the tide go out while a handful of giant stocks are still holding the surface up.
The discriminant model adds the second half. If the gauges tell you the tide is coming in, the MDA screen tells you where it is most likely to land. The flows favor particular profiles, a certain size, a certain valuation and momentum signature, the very characteristics the model is built to detect. Running the classifier across the whole market is like running a sonar scan for the clusters the money is already moving toward, so that you can position ahead of the flow rather than chasing it after the fact.
A Macro Checklist to Keep Beside the Gauges
I will leave you with the short set of questions I keep in view, not to trade off directly, but to size my risk and to know when to respect a turning tide. What is the Fed doing, adding liquidity or draining it? Are corporate buyback windows open, or is the market heading into an earnings-season blackout that removes a major buyer? Are fund flows running risk-on or risk-off? Where are interest rates, and are they rising quickly enough to pull money out of stocks and to make buybacks expensive? Is the carry trade stretched, the kind of quiet leverage that unwinds all at once? And above all, is the market’s risk appetite expanding or contracting?
You do not need a precise answer to any of these. That is the point of the gauges, which read the net result of all of them at once so you do not have to model each by hand. But keeping the questions in view changes how you carry risk. When the largest flows are with you, you can let breakouts run. When one of them turns, you tighten up and you believe the gauges when they flash, because you understand the size of the force now pushing against you. It is the same lesson the whole series keeps teaching, stated at its largest scale.
You may have the best stock in the world, but if the money flows are not with you, it will not move, and the flows in this chapter are the largest money flows there are.
These currents also connect the frontier chapters on either side of this one. The crypto and cross-asset momentum I described earlier drink from the very same pool of liquidity and risk appetite, which is why a tightening Fed or a risk-off mood can pull down stocks, crypto, and commodities together. Momentum is not only a pattern inside the stock market. It is the footprint of human capital in motion across every market at once, and the three flows are simply where that motion is largest and easiest to see.
Conclusion
This is an excerpt from my coming book based on a revisit of prior articles still very much alive and in force today. Many of my 2,000+ articles are available in the Members’ Library organized by subject. Ideally the organization of my material in my coming publications will add even more value to your investing goals in a concise and more structured way for you to benefit.
Wish you the very best in all your trades!
– JD Henning